Introduction
For almost 30 years, David had built his life around his business.
What started as a small UK commercial building-services company had grown into a substantial enterprise providing specialist energy, engineering and maintenance solutions to corporate clients. David remained its majority shareholder and was still closely involved in the relationships and decisions that mattered most.
By his early sixties, however, his priorities were changing.
His children were grown up and building lives of their own. David and his wife had spent years fitting holidays and family time around the demands of the company. They were now ready to decide where they wanted to live without the business making that decision for them.
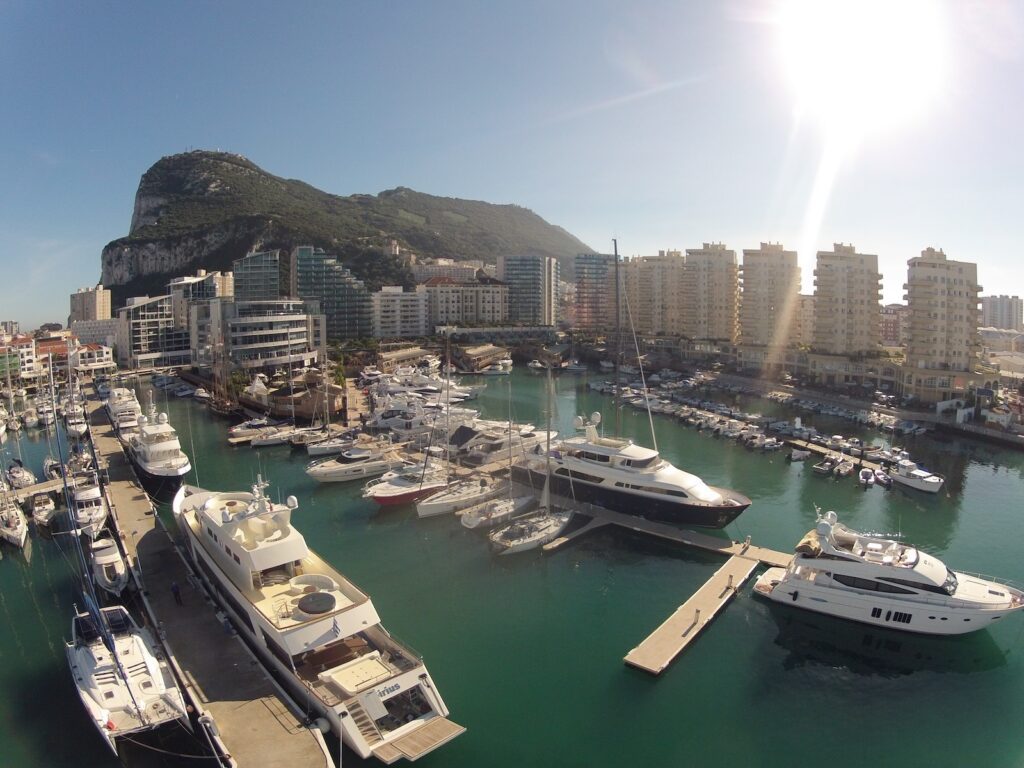
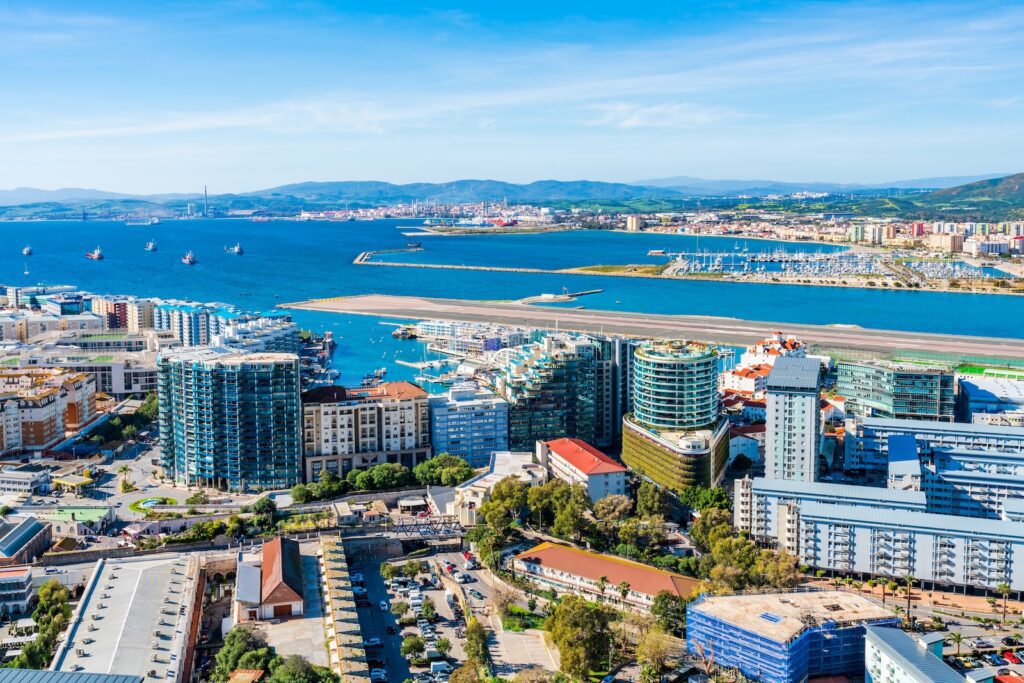
Gibraltar entered the conversation as somewhere they could genuinely imagine making home. They liked its climate, English-speaking environment and proximity to southern Spain, while David could remain accessible to his UK business when necessary.
At the same time, he had begun receiving approaches about the company. There was no agreed buyer, price or completion date, but a future sale was becoming increasingly realistic.
Rather than wait for a transaction to determine the family’s timetable, David began planning while he still had choices.
He and his wife moved to Gibraltar and David secured Category 2 status several years before serious negotiations began over a potential sale of the business for approximately £12.5 million.
This is the story of what happened next.
Article Summary
David and his wife relocated to Gibraltar several years before serious negotiations began over the potential £12.5 million sale of his UK business.
Category 2 Gibraltar became part of a wider strategy covering his UK tax residence, continuing business interests, £250,000–£300,000 annual dividend income, investments and eventual exit.
The defining feature of the case is timing: the family established its new life before the business sale became a live transaction.
Key Takeaways
David’s experience highlights several important considerations for UK entrepreneurs contemplating Category 2 Gibraltar before a future business exit:
- David and his wife chose Gibraltar as somewhere they genuinely wanted to live, independently of the anticipated sale.
- The relocation took place several years before serious negotiations with a purchaser.
- Category 2 Gibraltar was selected after considering David’s wealth, income and longer-term circumstances.
- Continuing ownership of a UK company meant his UK tax residence and business activities required separate consideration.
- Annual dividends of approximately £250,000–£300,000 created significant cross-border tax and investment-planning considerations.
- Diversifying family wealth before the sale reduced its dependence on one privately owned company.
- Gibraltar does not impose capital gains tax, but that alone does not determine the UK tax treatment of a business disposal.
- Beginning early gave David something particularly valuable: time to make major decisions before a purchaser imposed a commercial deadline.
David’s Story at a Glance
| Feature | David and His Family |
| Client | British entrepreneur in his early sixties |
| Family | Married with adult children |
| Business | UK commercial building-services company |
| Business activity | Specialist energy, engineering and maintenance solutions for corporate clients |
| Role | Founder, majority shareholder and senior decision-maker |
| Ownership period | Almost three decades |
| Annual dividends | Approximately £250,000–£300,000 |
| Family objective | Establish a genuine long-term life outside the UK |
| Destination | Gibraltar |
| Gibraltar status | Category 2 |
| Business exit | Not imminent when relocation planning began |
| Potential sale | Approximately £12.5 million |
| Investment objective | Build diversified family wealth beyond the company |
| Central challenge | Coordinate relocation, UK residence, business ownership, income, investments and eventual exit |
| Position today | Living in Gibraltar while discussions over the potential business sale progress |
| Key lesson | Plan while you still control the timetable |
Category 2 applicants also need suitable Gibraltar accommodation. Visit our Property in Gibraltar Guide.
The Decision David and His Family Made Before the £12.5m Exit
David was not ready to retire. He still enjoyed business, but an experienced management team meant he no longer needed to organise his family’s life around the company.
Potential buyers had also begun showing interest. After almost three decades of ownership, David could see that the business might eventually become a substantial liquidity event.
He and his wife did not want to wait for that event before deciding what came next.
Their children were independent and they were ready for a different life. The key question became simple: would they still choose Gibraltar if the company were never sold?
For a practical overview of what the move could mean for David and his family, visit our Living in Gibraltar Guide.
Planning Your Exit Before a Buyer Appears?
A business sale can compress years of decisions into months.
Book My Free 15-Minute Strategy Assessment
Limited private strategy slots available each week.
Trusted by UK nationals globally.
Prefer to speak directly? Tel: +44 208 058 8937.
Alternatively, email connect@adviceforexpats.com
Why David and His Wife Chose Gibraltar H2
Gibraltar offered David and his wife an English-speaking environment, warmer climate, easy access to southern Spain and good connections with the UK.
For David, remaining accessible to his UK business was important. For both of them, Gibraltar also had to work as a genuine long-term home rather than simply a tax-efficient location.
David’s wealth, £250,000–£300,000 annual dividend income and potential business sale then made the financial structure of the move important.
That brought Category 2 Gibraltar into the planning.
For the wider practical requirements of relocating, visit our Moving to Gibraltar from UK Guide.
Why Category 2 Gibraltar Became Central to the Plan
David’s wealth, £250,000–£300,000 annual dividends and potential business sale made Category 2 Gibraltar particularly relevant.
The regime provides qualifying high-net-worth individuals with greater certainty over their Gibraltar tax liability, subject to eligibility, accommodation and minimum tax requirements.
However, Category 2 status did not determine David’s UK tax residence or the UK tax treatment of his continuing business interests and eventual sale. Those issues required separate planning.
For eligibility, tax limits and application requirements, visit our Category 2 Gibraltar Guide.
Why Category 2 Fitted David’s Circumstances
| Question | David’s Position | Why It Mattered |
| Was he a high-net-worth individual? | Yes | Category 2 is a specialist regime for qualifying HNW individuals |
| Did he intend genuinely to live in Gibraltar? | Yes | Gibraltar was intended to become the family’s long-term home |
| Did he have substantial recurring income? | Yes | £250,000–£300,000 annual company dividends made tax planning material |
| Did he still own a UK business? | Yes | UK residence and continuing business activity required separate analysis |
| Was a business sale imminent? | No | Planning could begin before a purchaser controlled the timetable |
| Was a future liquidity event possible? | Yes | A later sale could convert concentrated business wealth into substantial liquid capital |
| Was tax the sole reason for moving? | No | The relocation had to work for David and his wife independently of the eventual sale |
Moving Years Before the Business Sale
David and his wife moved to Gibraltar several years before serious sale negotiations began.
This gave them time to establish Gibraltar as their home while David continued owning his UK business.
The move did not, however, determine his UK tax position. UK days, working patterns and ties still required careful management under the UK Statutory Residence Test, alongside the temporary non-residence rules.
For more detailed guidance on UK residence when emigrating, visit our Leaving the UK Guide.
The Planning Sequence
| Stage | What Happened | Why the Sequence Mattered |
| 1. Family decision | David and his wife decided they wanted a long-term life outside Britain | Relocation was not dependent upon a business sale |
| 2. Destination | Gibraltar became their preferred home | Lifestyle and financial considerations could be assessed together |
| 3. Residency planning | Category 2 was identified as appropriate | Specialist status was considered before implementation |
| 4. UK departure | UK residence and continuing ties required separate planning | Gibraltar residence alone was insufficient |
| 5. Business continuity | David retained ownership and remained selectively involved | The company did not need to be sold merely because he moved |
| 6. Wealth diversification | Surplus income could be invested beyond the business | Family wealth gradually became less concentrated |
| 7. Sale discussions | A serious potential purchaser emerged later | The family structure already existed before negotiations became material |
| 8. Potential exit | Discussions now contemplate approximately £12.5m | Post-sale investment and succession planning can build on an existing framework |
Running a UK Business While Living in Gibraltar
David remained majority shareholder after moving to Gibraltar, while his management team assumed greater day-to-day responsibility.
He still returned to the UK when necessary, so his UK days, work and continuing ties needed careful monitoring under the UK Statutory Residence Test.
The change also supported his eventual exit. A business capable of operating without its founder’s daily involvement was better positioned for a future sale.
Still Tied to Your UK Business?
UK workdays and business ties can undermine an otherwise carefully planned departure. Know where you stand before they become a tax problem.
Book My Free 15-Minute UK Residence Assessment
Limited private strategy slots available each week.
Trusted by UK nationals globally.
Prefer to speak directly? Tel: +44 208 058 8937.
Alternatively, email connect@adviceforexpats.com.
How David’s £250,000–£300,000 Annual Dividends Fitted Into the Plan
David continued receiving approximately £250,000–£300,000 a year in dividends from his UK company after relocating.
Their tax treatment had to be considered alongside his UK residence and Category 2 status. The income also provided capital to diversify family wealth beyond the business.
Rather than waiting for the eventual sale, David could begin building a separate investment portfolio while he still owned the company.
Building Wealth Outside the Family Business
David’s wealth remained heavily concentrated in his company. His annual dividends provided an opportunity to change that before the sale.
Surplus income was progressively invested outside the business, building a diversified portfolio around the family’s future income, liquidity and succession planning needs.
This also meant that a future £12.5 million sale could be incorporated into an existing wealth planning strategy rather than invested from scratch immediately after completion.
For more on managing wealth after relocation, visit our Wealth Management Guide.
Is Too Much of Your Wealth Still in Your Business?
A sale can turn decades of concentrated business wealth into cash overnight. Have your investment strategy ready before the proceeds arrive.
Book My Free 15-Minute Post-Sale Wealth Assessment
Limited private strategy slots available each week.
Trusted by UK nationals globally.
Prefer to speak directly? Tel: +44 208 058 8937.
Alternatively, email connect@adviceforexpats.com.
When the £12.5m Buyer Finally Arrived
Several years after the move, a serious potential purchaser emerged, valuing David’s business at approximately £12.5 million.
By then, David and his wife were established in Gibraltar, his Category 2 status was in place and part of the family’s wealth had already been diversified outside the company.
The sale remained subject to negotiation and specialist tax advice, but David was not trying to relocate in response to a buyer’s timetable.

What the Business Sale Could Mean for David and His Family
If the £12.5 million sale completes, David will move from concentrated business ownership to managing substantial liquid wealth.
The priorities will change accordingly: how much capital to retain, the income the family needs, appropriate investment risk and how widely to diversify.
Longer term, the emphasis is likely to shift from creating wealth to preserving it, generating sustainable income and succession planning for his family.
Before and After a Potential £12.5m Sale
| Planning Area | Before the Sale | After a Completed Sale |
| Principal wealth source | Private UK company | Predominantly liquid/investment capital |
| Regular cash flow | Company dividends | Portfolio and other income |
| Concentration risk | High exposure to one business | Opportunity for broad diversification |
| David’s role | Owner and strategic decision-maker | Potentially no operational role |
| Investment objective | Build wealth beyond the company | Preserve and manage substantial liquid capital |
| Liquidity | Much of wealth relatively illiquid | Significantly greater liquidity |
| Family planning | Preparing for eventual exit | Funding lifestyle and longer-term family objectives |
| Succession | Business and personal wealth intertwined | Greater scope to plan around liquid/non-business assets |
| Main risk | Dependence on business value | Poor deployment of sale proceeds |
David’s earlier investment planning now becomes particularly useful. A framework already exists and can be reassessed and expanded when the sale proceeds arrive.
The sale may end his ownership of the company, but the family’s financial planning continues.
The UK Tax Issues Business Owners Cannot Ignore
Gibraltar does not impose capital gains tax, but moving there does not automatically remove a UK entrepreneur from UK taxation.
Four issues are particularly relevant to David’s potential sale.
UK Tax Residence
Gibraltar residence and Category 2 status do not determine UK tax residence.
The UK Statutory Residence Test considers UK days, work and relevant ties separately for each tax year. This is particularly important where a business owner continues working or visiting the UK.
For the wider Gibraltar position, visit our Taxes in Gibraltar Guide.
Temporary Non-Residence
Returning to the UK can affect the treatment of certain income and gains realised while abroad.
The temporary non-residence rules can therefore be particularly important where an entrepreneur sells a company and later returns to the UK.
For the detailed rules, visit HMRC: Temporary Non-Residents and Capital Gains Tax.
Capital Gains Tax
Gibraltar has no capital gains tax.
That does not mean every UK entrepreneur can move to Gibraltar and sell a company tax-free. David’s UK residence, timing, circumstances and any subsequent return to the UK must be considered before determining the treatment of the disposal.
Inheritance and Succession Tax
Since 6 April 2025, UK Inheritance Tax on overseas assets has been based on long-term UK residence rather than the former domicile regime.
Broadly, someone resident in the UK for at least 10 of the previous 20 tax years can remain within the long-term residence regime for 3–10 years after leaving the UK, depending on their residence history.
David’s post-sale planning therefore needs to consider both investment and succession tax implications.
A £12.5m Exit Changes More Than Your Tax Bill
A business sale can transform decades of concentrated wealth into liquid capital overnight. Plan how the proceeds will support you and your family before completion.
Book My Free 15-Minute Business Exit Assessment
Limited private strategy slots available each week.
Trusted by UK nationals globally.
Prefer to speak directly? Tel: +44 208 058 8937.
Alternatively, email connect@adviceforexpats.com.
What Other UK Entrepreneurs Can Learn From David’s Move
David’s circumstances are unusual in scale, but the planning questions apply to many UK business owners considering relocation before an eventual exit:
- Where do you genuinely want to live? The destination must work independently of tax.
- When will your UK tax residence cease? Overseas residence does not determine UK residence.
- What involvement will you retain in the business? Consider UK work, visits and continuing responsibilities.
- How will you fund life before the sale? Plan salary, dividends and investment income.
- How concentrated is your wealth? Consider diversifying before the business is sold.
- What happens to the sale proceeds? Decide how future capital should be invested and used.
- Could you return to the UK? Understand the potential tax consequences before leaving.
David’s central lesson is simple: plan the relocation, business exit and family wealth before a purchaser controls the timetable.
Why Choose Advice for Expats?
Moving abroad before selling a business can involve residency, UK tax, investments and succession planning.
Advice for Expats helps UK entrepreneurs coordinate these decisions and, where specialist regulated advice is required, connects them with appropriate tax, legal and financial professionals.
The objective is simple: one coordinated relocation strategy rather than disconnected advice.
Frequently Asked Questions
These questions cover key issues for UK entrepreneurs considering Category 2 Gibraltar before selling a business.
What is Category 2 Gibraltar?
Category 2 is a specialist Gibraltar tax status for qualifying high-net-worth individuals. Applicants must meet the regime’s wealth, accommodation and other eligibility requirements. It provides a capped framework for Gibraltar tax on assessable income and is designed for qualifying individuals establishing residence in Gibraltar.
What is the minimum wealth requirement for Category 2 Gibraltar?
For new applicants, the Gibraltar Government announced in June 2026 that the minimum net-wealth requirement would increase from £2 million to £5 million, alongside an increase in the application fee to £5,000. Applicants must also meet the other Category 2 eligibility and accommodation requirements.
Can I own a UK company after moving to Gibraltar?
Yes. Moving to Gibraltar does not itself prevent you from retaining shares in a UK company. However, continuing directorship duties, UK working days, accommodation, family connections and time spent in Britain may affect your UK tax position and should be reviewed separately.
Does moving to Gibraltar automatically make me non-UK tax resident?
No. UK tax residence is determined under the UK Statutory Residence Test, not by possession of Gibraltar residence documentation. The SRT examines automatic residence tests and, where necessary, UK ties and day counts. Each tax year is considered separately.
Does Gibraltar charge Capital Gains Tax when I sell my business?
Gibraltar does not impose Capital Gains Tax. However, a UK entrepreneur living in Gibraltar may still need to consider UK tax residence, temporary non-residence and other UK rules before concluding that a particular business disposal falls outside UK CGT.
How long before selling my company should I move to Gibraltar?
There is no universal number of months or years that guarantees a particular tax outcome. The relevant factors include your UK residence history, UK ties, work, intended length of non-residence and future plans. David’s case illustrates the practical advantage of planning well before a transaction becomes imminent.
Can I return to the UK after selling my business in Gibraltar?
Yes, but returning can have tax consequences. Where the temporary non-residence rules apply, certain income and gains realised while abroad can become taxable in the year of return. HMRC states that these rules can apply to periods of non-residence lasting five years or less, subject to the detailed conditions.
Does moving to Gibraltar remove UK Inheritance Tax immediately?
Not necessarily. Since 6 April 2025, UK IHT on overseas assets is principally linked to long-term UK residence. Depending on previous UK residence, someone leaving Britain can remain within the long-term residence regime for between three and ten tax years.
People Also Ask
These questions cover other common Category 2 and Gibraltar queries.
How much tax does a Category 2 individual pay in Gibraltar?
Current Gibraltar Income Tax Office guidance gives a minimum Category 2 annual tax liability of £37,000 and a current maximum of £42,380. Gross assessable income is capped at £118,000 for this purpose. The precise liability depends on the individual’s circumstances and applicable rules.
Do I have to live in Gibraltar to have Category 2 status?
Category 2 applicants must have approved residential accommodation in Gibraltar available for their exclusive use for the whole year of assessment and satisfy the regime’s other conditions. Category 2 tax status and Gibraltar’s wider residence rules should nevertheless be considered separately.
How many days can I spend in the UK after moving to Gibraltar?
There is no single safe UK day limit applicable to everyone. Under the Statutory Residence Test, the permitted number can depend on previous residence, work and UK ties. For some former UK residents, increasing ties means UK residence can arise with progressively fewer UK days.
Can I continue working in Britain after becoming resident in Gibraltar?
Yes, but UK work can affect the Statutory Residence Test. HMRC considers both time spent in Britain and working patterns, with specific tests applying to UK and overseas work. Entrepreneurs who remain active in their companies should therefore record UK workdays as well as total UK days.
Can I sell shares in a UK company while living in Gibraltar?
Yes. Living in Gibraltar does not prevent you from selling shares in a UK company. However, the tax treatment depends on your circumstances, including UK tax residence and potential temporary non-residence rules. Gibraltar’s absence of capital gains tax does not by itself determine the UK tax treatment of the sale.
What happens financially after selling a business for millions?
A major sale can convert an illiquid, concentrated business interest into substantial liquid capital. The owner then needs to consider cash reserves, investment diversification, sustainable income, risk, succession and estate planning. Ideally, those decisions begin before completion rather than while substantial proceeds are sitting unallocated.
Useful Resources
For further official guidance:
Gibraltar Income Tax Office: Qualifying Individuals:
Official guidance on Category 2 tax limits and liabilities.
HMRC: Tax if You Return to the UK:
Official guidance on returning to the UK and temporary non-residence.
Start Your Journey
David and his wife moved to Gibraltar years before the potential £12.5 million sale became a live transaction.
That gave them time to establish their home, address David’s Category 2 and UK residence position, diversify family wealth and prepare for an eventual business exit.
The lesson is simple: if selling your business is on the horizon, start planning while you still control the timetable.
Planning a Future Business Sale?
Your relocation, UK tax position and family wealth should be considered before a buyer sets the deadline.
Book My Free 15-Minute Gibraltar Strategy Assessment
Limited private strategy slots available each week.
Trusted by UK nationals globally.
Prefer to speak directly? Tel: +44 208 058 8937.
Alternatively, email connect@adviceforexpats.com.